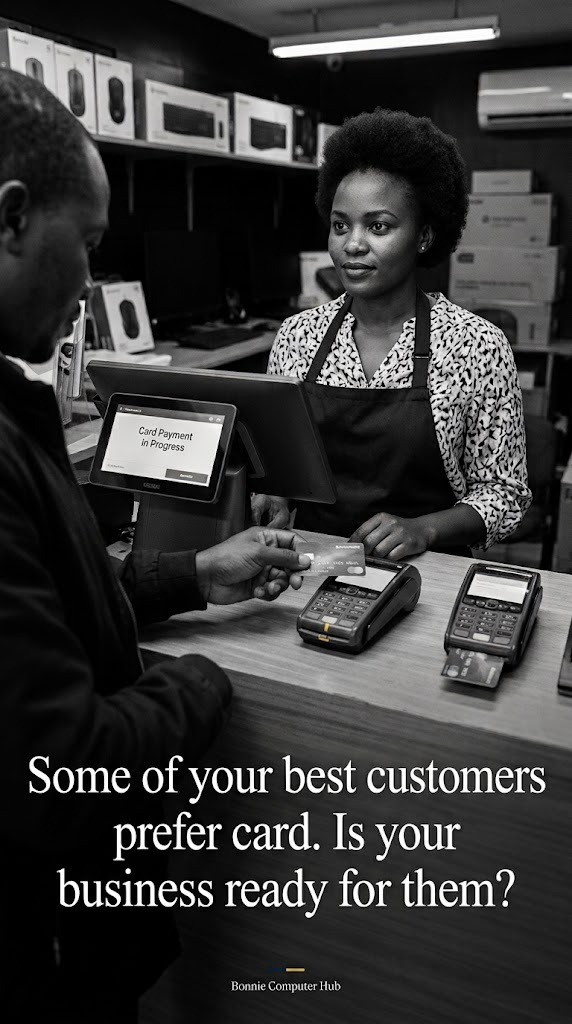
CARD PAYMENT INTEGRATION — WHAT OPTIONS EXIST FOR KENYAN BUSINESSES.
CARD PAYMENT INTEGRATION — WHAT OPTIONS EXIST FOR KENYAN BUSINESSES.
Card payments in Kenya are growing.
Not fast enough to replace M-Pesa as the dominant payment method. But fast enough that a business without card capability is turning away a meaningful segment of customers every day.
Salaried professionals. Corporate buyers. Diaspora visitors. International tourists. These customers prefer card. And if your POS cannot accept it, they will find a business that can.
Who uses card payments in Kenya
✅ Salaried employees paying from their bank account via debit card
✅ Corporate buyers whose companies issue Visa or Mastercard business cards
✅ Diaspora visitors who carry international cards
✅ International tourists and business travellers
✅ High value purchasers who prefer not to carry large cash amounts
The two types of card payment setup
Physical card terminal
A physical device the customer taps, inserts, or swipes their card on.
✅ Contactless — NFC tap for cards and phones with Apple Pay or Google Pay
✅ Chip and PIN — customer inserts card and enters PIN
✅ Integrated with POS — amount sent automatically, confirmation received back
Who provides card terminals in Kenya:
✅ Equity Bank
✅ KCB
✅ Cooperative Bank
✅ Pesapal — provides terminals alongside their gateway
✅ DPO Group — terminal and gateway combined
Online card payment gateway
For businesses that also sell online or want a software only card solution.
✅ Customer enters card details on a secure payment page
✅ Gateway processes payment in real time
✅ Confirmation sent to POS and customer
Payment gateways available in Kenya
✅ Pesapal — Kenya's most widely used, supports M-Pesa and cards
✅ DPO Group — strong East Africa presence
✅ Flutterwave — pan-Africa, good for regional ambitions
✅ iPay Africa — built specifically for African payment methods
✅ Stripe — best for businesses selling to international customers
Card payment costs
Every card transaction carries a processing fee of typically 1.5% to 3.5% depending on gateway and card type. Factor this into your pricing decisions.
The right integration approach
✅ Integrated — POS sends amount to terminal automatically, confirmation comes back, one unified record
✅ Semi-integrated — cashier manually enters amount on terminal, then confirms in POS
✅ Standalone — terminal operates independently, manual reconciliation at end of day
Always aim for integrated. Manual entry creates amount mismatch risk and reconciliation burden.
Is your business accessible to every customer who wants to pay you — or only to those carrying cash or M-Pesa?
🌐 www.bonniecomputerhub.co.ke
📲 +254 729 820 689
© Bonnie Computer Hub | Empowering Through TechnologyCARD PAYMENT INTEGRATION — WHAT OPTIONS EXIST FOR KENYAN BUSINESSES.
Card payments in Kenya are growing.
Not fast enough to replace M-Pesa as the dominant payment method. But fast enough that a business without card capability is turning away a meaningful segment of customers every day.
Salaried professionals. Corporate buyers. Diaspora visitors. International tourists. These customers prefer card. And if your POS cannot accept it, they will find a business that can.
Who uses card payments in Kenya
✅ Salaried employees paying from their bank account via debit card
✅ Corporate buyers whose companies issue Visa or Mastercard business cards
✅ Diaspora visitors who carry international cards
✅ International tourists and business travellers
✅ High value purchasers who prefer not to carry large cash amounts
The two types of card payment setup
Physical card terminal
A physical device the customer taps, inserts, or swipes their card on.
✅ Contactless — NFC tap for cards and phones with Apple Pay or Google Pay
✅ Chip and PIN — customer inserts card and enters PIN
✅ Integrated with POS — amount sent automatically, confirmation received back
Who provides card terminals in Kenya:
✅ Equity Bank
✅ KCB
✅ Cooperative Bank
✅ Pesapal — provides terminals alongside their gateway
✅ DPO Group — terminal and gateway combined
Online card payment gateway
For businesses that also sell online or want a software only card solution.
✅ Customer enters card details on a secure payment page
✅ Gateway processes payment in real time
✅ Confirmation sent to POS and customer
Payment gateways available in Kenya
✅ Pesapal — Kenya's most widely used, supports M-Pesa and cards
✅ DPO Group — strong East Africa presence
✅ Flutterwave — pan-Africa, good for regional ambitions
✅ iPay Africa — built specifically for African payment methods
✅ Stripe — best for businesses selling to international customers
Card payment costs
Every card transaction carries a processing fee of typically 1.5% to 3.5% depending on gateway and card type. Factor this into your pricing decisions.
The right integration approach
✅ Integrated — POS sends amount to terminal automatically, confirmation comes back, one unified record
✅ Semi-integrated — cashier manually enters amount on terminal, then confirms in POS
✅ Standalone — terminal operates independently, manual reconciliation at end of day
Always aim for integrated. Manual entry creates amount mismatch risk and reconciliation burden.
Is your business accessible to every customer who wants to pay you — or only to those carrying cash or M-Pesa?
🌐 www.bonniecomputerhub.co.ke
📲 +254 729 820 689
© Bonnie Computer Hub | Empowering Through Technology